Finance Your Basement
with a manageable monthly payment
Move forward now without draining all your cash at once, while still keeping the flexibility to pay it down faster later.
Finish the basement now instead of waiting years to save the full amount
Turn a large renovation cost into a more manageable monthly payment
Protect savings while still moving forward on the project
Smart financing lens
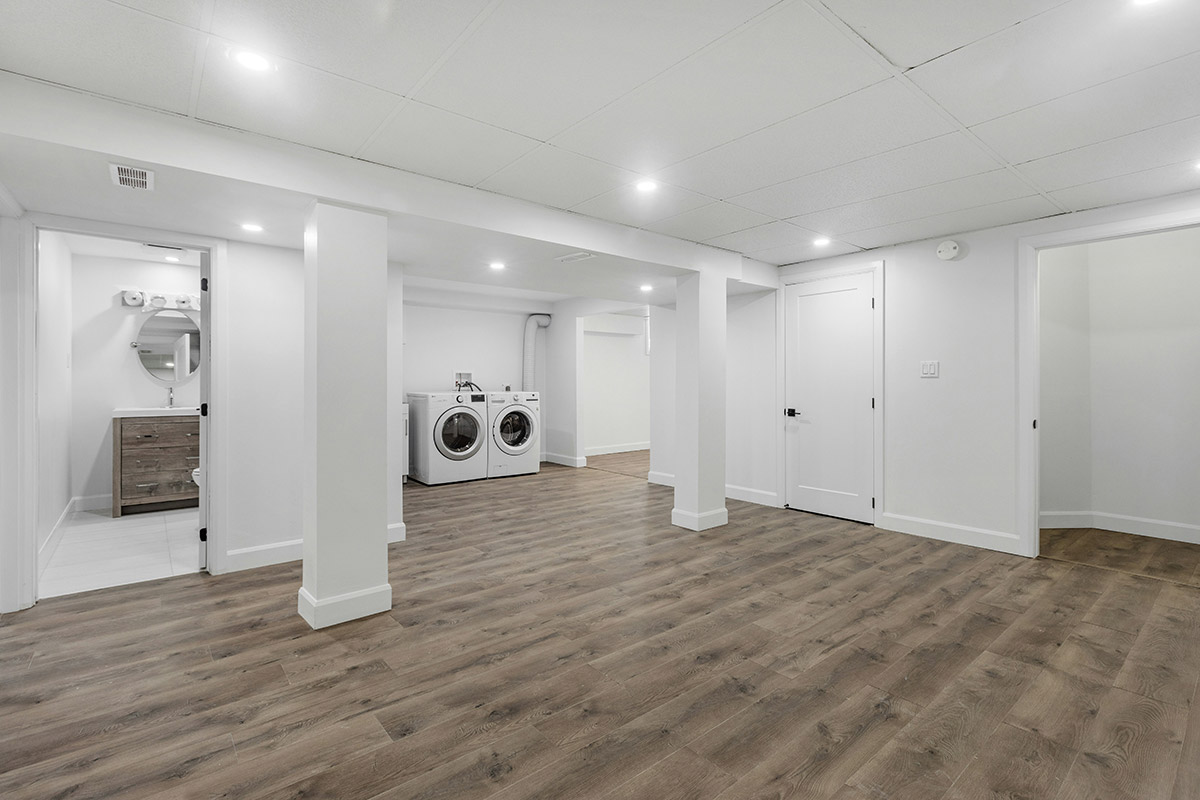
Why this works
Get the basement now without draining all your cash today
Use financing to make the project happen now and keep your savings intact while the space starts working for you sooner.
Example payment
$592/month
Approx. $20/day
Deposit example: $19,210
You can also review our renovation financing overview.
At a glance
The financing setup most homeowners are actually looking at
These are the core assumptions behind the payment examples on this page, shown in plain English.
No prepayment penalties
Pay it down early if you want.
Monthly-first setup
Built around a manageable payment.
60-month promo term
This is the most common structure we show.
Maximum amortization
Often used to keep the required monthly lower.
O.A.C.
Final approval still depends on profile and lender.
Finance incl. HST
The calculator reflects the full project amount.
Open loan basics
What is an open loan?
An open loan lets you move forward on a basement renovation now and spread the cost over time without locking yourself into carrying the balance for the full schedule.
That distinction matters. Many homeowners hear a long amortization period and assume they are trapped for the full duration. With an open loan, the setup mostly exists to keep the required monthly payment manageable so the basement can get done now. It does not remove your ability to make extra payments or fully exit early.
This is why open-loan financing can work well for basement projects with a smarter payoff plan behind them. You can keep monthly pressure manageable now, then use a bonus, refinance, or early payoff strategy later if it still makes sense.
The practical takeaway
Renovate now and spread the cost over time
Keep the required payment manageable
Make extra payments when cash flow allows
Pay it off early with no prepayment penalty
Use financing as a bridge, not necessarily a lifelong balance
Process
How it works
The financing path is straightforward. The key is understanding how rate support, term, and amortization shape the required monthly.
Choose your renovation budget
Start with the full basement project number, including 13% HST, so the payment conversation reflects reality.
Estimate the monthly properly
Look at the real financed amount including HST, then structure the payment around the promo program and amortization period.
Choose the promo program
Most files are shown at 9.99%, 8.99%, or 7.99% depending on the borrower and how aggressively we want to support the monthly.
Maximize amortization if needed
A longer amortization period usually lowers the required monthly payment, which is why many real files are shown at the maximum.
Complete the renovation
Use financing to move forward now so the basement starts adding value and utility sooner, not years later.
Pay normally or exit early
That is the core benefit of an open loan: you can make the required payment now and still clear it early without a prepayment penalty.
Why homeowners use it
Why homeowners finance a basement instead of waiting
The appeal is usually not about borrowing for its own sake. It is about making the project happen sooner without wrecking cash flow.
Get the basement done now
Many homeowners finance because they want the finished space now, not after years of trying to save the full amount in cash.
Preserve savings
Financing can protect emergency reserves and day-to-day liquidity instead of draining cash all at once for a basement project.
Unlock rental potential
For some homeowners, a legal or rental-oriented basement creates income potential that would otherwise be delayed by waiting.
Keep your exit flexible
An open structure gives you breathing room now while keeping a refinance, bonus payment, or early payoff strategy on the table later.
Calculator
Basement payment calculator
Use this to pressure-test what it could look like to finish the basement with a manageable monthly payment instead of waiting until the full cost can be paid in cash.
This uses a common financing example: 9.99%, a 60-month promo term, monthly payments, and a longer amortization period to keep the required monthly lower.
Total financed (incl. HST)
$96,050
Start with the payment first. Open the setup only if you want to pressure-test the assumptions behind it.
Basement payment estimate
$926/ month
Approx. $31/day
Instead of putting down $19,210 today
View details
Typical example shown at 9.99%, 60-month promo term, monthly payments, and 240-month amortization.
O.A.C. Illustrative only. Actual rates, terms, and APRs depend on approval through Financeit.
Cost of waiting
Waiting has a cost too
Financing has a cost, but waiting often has one too. For many homeowners, the more useful question is whether delaying the basement makes life or property plans harder in the meantime.
A delayed basement often means delayed living space, delayed rental potential, and more time living with a part of the house that is not helping the family the way it could.
That is why many homeowners do not frame the decision as "cash or no project." They frame it as whether a manageable monthly payment is worth getting the space now.
The point is not to push financing for its own sake. It is to understand whether financing helps unlock a basement project that meaningfully improves daily life, home value, or income potential sooner.
Basement decision lens
Get the extra living space now
Avoid draining all your savings at once
Spread a large project into monthly payments
Keep the option to pay down faster later
Smart basement financing
Open loans work best when they make the project possible now
The strongest use case is not borrowing forever. It is using financing as a flexible tool to get the basement done now while keeping control over when and how the balance gets reduced.
Annual cash events
Bonuses, commissions, and tax refunds can be used to reduce principal meaningfully without changing the original monthly structure.
Refinance after the basement is complete
If the renovation improves the home in a material way, some homeowners later revisit their capital stack rather than carrying the open loan indefinitely.
Control over timing
The core advantage is optionality. You are not forced into an all-cash decision today, and you are not boxed out of a better payoff path later.
The point is not to glorify debt. The point is to use financing intelligently: make the basement possible now, preserve flexibility, and keep a realistic exit strategy in view from day one.
FAQ
Common questions about open-loan financing
Short answers for homeowners trying to decide whether financing is the right way to move ahead on a basement renovation.
An open loan is a financing structure that lets you make the required monthly payment while still keeping the option to pay down extra principal or clear the balance early without a prepayment penalty.
Use financing to get the basement done sooner, not keep it stuck on hold
A well-structured open loan can turn a basement renovation from a someday project into a realistic next step while still giving you control over how you reduce the balance later.
Disclaimer
O.A.C. (On Approved Credit). Illustrative only. Actual rates, terms, and APRs are determined by Financeit based on individual credit profiles.
Promotional and contractor-supported financing options may not be available in all cases. Deferred payment programs may accrue interest during the deferral period.