Ontario Renovation Financing
Get project guidance, understand your next steps, and move forward with the right renovation path.
We help you review your project requirements first, then coordinate the appropriate next step if financing makes sense.
Most homeowners don't pay for renovations upfront anymore
Most renovations today are not paid upfront. They are structured into manageable monthly payments, which is one reason bigger projects often become possible sooner than homeowners expect, especially for basement renovation projects.
How it works
Share what you are planning
Tell us about your scope, budget range, and project type so you can start with the right context.
See possible monthly payment options
Explore what monthly payment options could look like before deciding what feels workable.
Request a project review
Get project guidance and a plan that fits your budget.
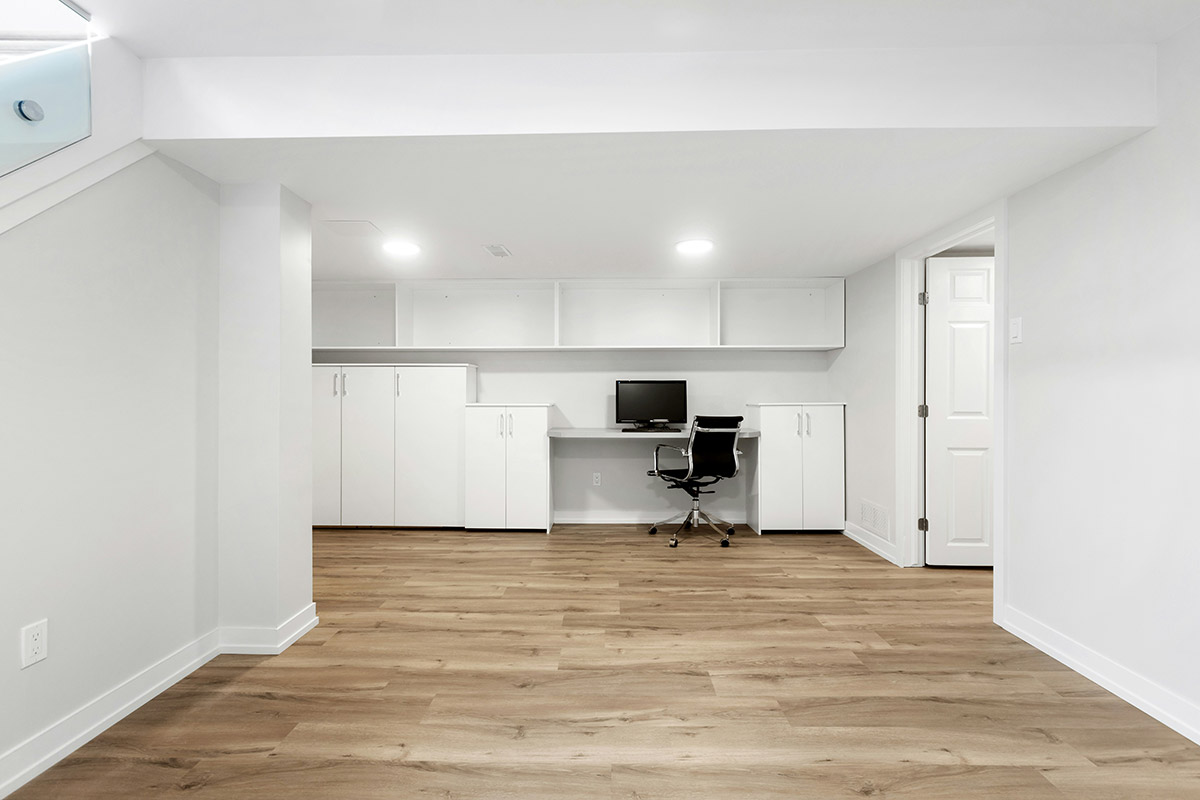
Monthly payment examples
These Ontario renovation financing examples help homeowners think in monthly terms instead of total sticker shock.
Illustrative scenarios only. Actual approval and terms depend on borrower profile, project scope, and lender review.
Basement renovation
$420-$860/mo
Typical range for a $50K-$80K project
Illustrative example only
Explore basement projectsKitchen renovation
$280-$690/mo
Typical range for a mid-range kitchen project
Illustrative example only
Explore kitchen projectsBathroom renovation
$180-$420/mo
Typical range for a standard renovation scope
Illustrative example only
Explore bathroom projectsLarger-project planning
Using home equity for larger renovations
For larger projects like legal basement apartments, garden suites, additions, or major remodels, home equity may become part of the planning conversation. Learn how to judge whether the renovation itself justifies using equity before committing.
Related guides: HELOC vs refinance, HELOC vs renovation financing, phased renovation financing, legal basement apartment financing, garden suite financing, and grants with home equity.
Financing mindset
How renovation financing works
Most people look at home renovation financing in Ontario like a car loan or mortgage. That is where the misunderstanding starts.
Old thinking
- What's the rate?
- What's the term?
- How long am I paying?
- This gets judged like a car loan
The shift
How open-loan financing actually works
Make the required monthly payment
Pay extra anytime
Extra goes toward principal
Total cost depends heavily on how long the balance is carried
Why this changes the decision
- The project is judged by monthly fit, not just sticker price
- Basement income may help offset payment
- Faster paydown may become realistic
- The exit path can look very different than people assume
This is where most homeowners misunderstand financing.
Open-loan financing changes the conversation. The minimum payment is only the starting point, extra payments can reduce principal sooner, and basement income may create a very different exit path than most homeowners assume.
Financing may be available through established providers such as Financeit, depending on the contractor and project.
If you want a deeper breakdown of payment flexibility, no-prepayment-penalty structure, and smarter payoff planning, see our open loan financing guide.
It also helps to compare monthly payments against overall renovation costs before deciding what feels realistic.
Control
Move forward without draining all your cash upfront.
Flexibility
Make the required payment, then push harder when it suits you.
Possibility
Judge the project by what works now, not just by the full sticker price.
Open loan financing
Want the deeper version of how renovation financing really works?
Our open-loan financing guide breaks down the part most homeowners miss: why the required monthly payment is only the starting point, how extra payments change the math, and why a flexible exit path matters.
Inside the guide
How open loans differ from standard monthly-payment thinking
Why no-prepayment-penalty flexibility changes the decision
How to think about payoff strategy instead of just rate
If monthly affordability is only part of the question, this is the page that gives the fuller picture.
What can be financed
Financing can make projects like these possible sooner and feel more manageable than most homeowners expect.
It can be a practical way to balance project scope, monthly affordability, and timing without feeling forced into an all-cash decision, whether you are planning basement renovations, kitchen renovations, or bathroom renovations.
Common financing questions
Do I need full cash upfront?
No - you do not always need the full renovation cost in cash upfront, and many homeowners use monthly-payment financing instead.
Can I explore options first?
Yes. The goal is to understand possible options before committing, not to force a project into the wrong structure.
Can projects be structured around a budget?
Often, yes. Scope, priorities, and project timing can usually be discussed with budget reality in mind.
Don't rule your renovation out before seeing what your monthly payment could look like
Monthly payment options can make a basement, kitchen, bathroom, or legal suite project feel more manageable without forcing a rushed decision.
Takes less than a minute - No obligation